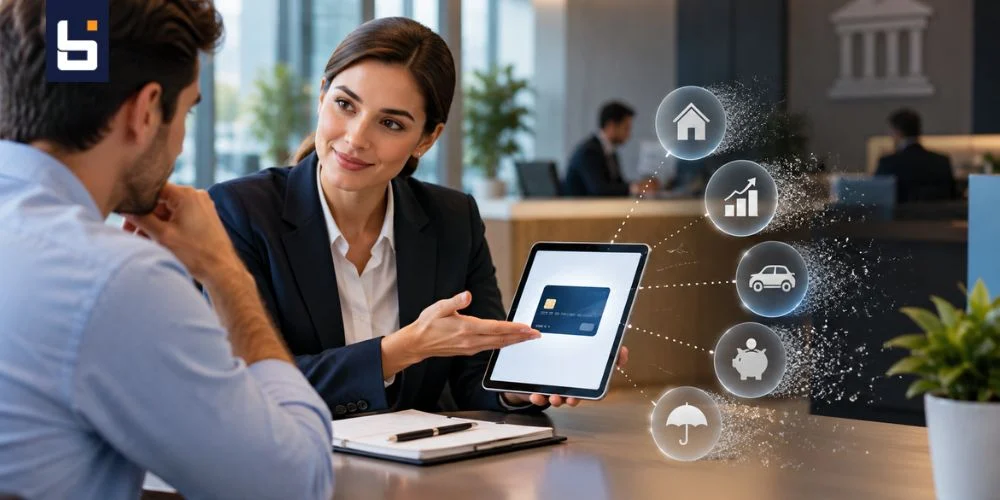
Banks often know which existing customers may be relevant for another product before a campaign begins. The customer segment has been identified, eligibility rules are established, and the offer is approved. Yet successful banking cross-selling still depends on something far more operational: reaching the customer, having a relevant conversation, and moving genuine interest to the right next step.
That is where a well-planned campaign can lose momentum. An opportunity identified in a CRM does not automatically become a conversation. A conversation does not automatically become an appointment, transfer, application, or sale.
The challenge is therefore often less about finding another cross-sell idea and more about executing the opportunities the bank has already identified. For a broader look at upselling and cross-selling in financial services, our earlier guide covers the wider strategy. Here, the focus is specifically on the execution gap that appears after an opportunity has already been identified.
Banking Cross-Selling Has an Execution Gap
The banking cross-sell execution gap is the loss of opportunity between identifying a relevant additional product for an existing customer and successfully moving that customer into the appropriate next conversation or action.
A bank may have sophisticated segmentation, customer data, campaign logic, and next-product models. Those capabilities help determine who may be relevant for an approved offer. They do not solve every step that follows.
The customer still needs to be reached. The conversation needs to make sense in context. Genuine interest needs to be recognized. Then the customer needs a clear route to a banker, specialist, appointment, digital application, or another approved next step. This distinction matters across financial services customer engagement. The value of customer data is ultimately limited by the organization’s ability to act on it consistently.
Capgemini’s Banking Top Trends 2026 identifies personalization as a growth driver and notes that banks are using data and AI to match products and communications more closely to individual customer needs. It also points to automation as a way to free relationship managers to spend more time on client engagement and cross-selling opportunities.
Where Good Cross-Sell Opportunities Get Lost
The weak point is not always the offer itself. In many programs, leakage occurs between campaign design and customer action. Five execution problems deserve particular attention.
1. The Customer Is Identified but Never Reached
An approved customer list has no commercial value if a significant portion of it is never worked properly. Internal relationship managers, branch teams, and sales specialists have competing priorities. Large campaigns can create more outreach than those teams can absorb. Calling may begin late, contact attempts may be inconsistent, or callbacks may depend on individual workloads.
This is where banking telesales becomes an operating-capacity question. A structured outbound customer engagement model can give approved campaigns clear ownership, defined contact attempts, consistent dispositions, and a repeatable customer follow-up process.
When that capacity problem becomes persistent, banks may also need to compare the economics and flexibility of outsourced telesales versus an in-house sales team.
2. The Conversation Starts With the Product Instead of the Customer
Cross-selling in banking works poorly when the conversation feels disconnected from the customer’s relationship with the institution. An approved offer may be relevant, but relevance still needs to be communicated appropriately. The customer should understand why the conversation is taking place, what the permitted offer involves, and what next step is available if there is genuine interest. That is different from pushing every eligible product simply because the customer’s name appears on a campaign list.
In its 2026 banking customer-experience research, EY India found that nearly 60% of surveyed customers expected AI-powered guidance to help with financial decisions, particularly budgeting, savings, and planning, rather than simply receiving sales-driven nudges. The study was based on more than 2,000 banking customers in India, so the finding should be viewed in that market context, but it reinforces the importance of relevance in customer engagement.
3. Interested Customers Have No Clear Next Step
Customer interest is only useful when the operating process knows what to do with it. One customer may need a specialist. Another may need an appointment with a financial advisor or relationship manager. Another may be ready for a permitted digital application journey. Some programs may allow an immediate transfer to the appropriate internal team. The handoff should be defined before outreach begins. If an interested customer is simply placed back into a general callback queue, the bank has created another opportunity for the conversation to stall.
Structured appointment setting services can support programs where the next step requires a scheduled specialist conversation. Our guide to appointment setting for financial advisors looks more closely at how that handoff can work when a specialist needs to take over.
4. Follow-Up Ends Before the Customer Is Ready
Not every interested customer will act during the first conversation. Some may ask to speak later. Others may want to review approved information first. A customer may start the next step but not complete it immediately. In each case, the campaign needs a defined follow-up path that stays within the bank’s contact rules, customer permissions, approved scripts, and compliance requirements.
Good customer follow-up should therefore be deliberate rather than dependent on individual memory. The campaign should define when another contact attempt is appropriate, which disposition triggers it, and when outreach should stop.
5. Activity Is Measured, but Progress Is Not
Call volume alone does not tell a bank whether a cross-sell program is working. Useful campaign measures may include:
-
- Contact rate and meaningful conversation rate
- Customer interest or qualified-interest rate
- Appointment or warm-transfer rate
- Follow-up completion and campaign conversion
- Quality, opt-out, complaint, and compliance indicators
The exact measures will depend on the product and operating model. The important point is to follow the customer from outreach to the intended next step rather than judging the program mainly by dialing activity.
From Identified Opportunity to Customer Action
| What the Bank Has Already Done | Execution Requirement | Desired Progress |
|---|---|---|
| Customer segment identified | Reach | Customer contacted |
| Relevant offer approved | Engage | Useful conversation established |
| Eligibility rules established | Identify interest | Customer wants an approved next step |
| Specialist route defined | Connect | Appointment, transfer, or permitted action |
| Campaign launched | Follow up | Opportunity progresses or reaches a clear disposition |
A cross-sell opportunity creates value only when each stage connects cleanly to the next.
What Does a Better Banking Cross-Sell Operating Model Look Like?
A strong operating model does not begin with more calls. It begins by defining what should happen to each approved customer opportunity from outreach through disposition.
Start With an Approved Audience
The bank determines the customer population, product, eligibility rules, exclusions, disclosures, contact permissions, and other campaign requirements. The execution team works within those boundaries.
Execute Structured Outreach
Approved customer lists should be worked according to the bank’s defined scripts, contact cadence, permitted channels, operating hours, and escalation rules. This is where scalable telesales services can add capacity when internal teams cannot consistently work the full campaign population.
Establish Genuine Interest
The objective is not to independently decide what financial product the customer should buy. Instead, the conversation should establish whether the customer wants to take the next permitted step within the bank’s approved offer and process.
Move the Customer Forward
Depending on the program, the next action could be a scheduled appointment, a warm transfer, a digital journey, further approved information, or a permitted telesales transaction. The transition should happen with context intact so the customer is not forced to repeat information unnecessarily.
Capture the Outcome
Every interaction should end with a meaningful disposition. Campaign teams should know whether the customer was contacted, interested, transferred, scheduled, asked for follow-up, declined, or reached another approved outcome. This creates feedback for both campaign management and future customer engagement.
Telesales Should Extend the Bank’s Strategy, Not Replace It
Outsourced financial services telesales should operate as an execution layer around the financial institution’s approved strategy. A telesales partner should execute a bank-approved customer engagement model. It should not independently determine which regulated financial product a customer should receive.
The bank retains ownership of product strategy, customer eligibility, pricing, underwriting, disclosures, regulatory policy, and any activity that must be completed by licensed or authorized personnel. An operating partner may support approved outreach, customer follow-up, scripted product information, interest identification, appointment setting, warm transfers, permitted sales activity, quality monitoring, and campaign reporting according to the agreed program.
Banks considering this type of model can explore outsourced upselling and cross-selling services as part of the customer-contact layer rather than as a substitute for the bank’s product or compliance functions. The same principle applies more broadly to how financial services firms use outsourced support to scale: the goal is to add operating capacity while preserving control of the decisions that belong with the financial institution.
What Stays With the Bank vs. What Can Be Outsourced
| The Bank Owns | An Outsourcing Partner Can Execute Within the Approved Model |
|---|---|
| Customer and product strategy | Approved outbound customer outreach |
| Eligibility rules and exclusions | Customer contact and campaign follow-up |
| Product terms and pricing | Approved product information and scripting |
| Underwriting and credit decisions | Identification of customer interest |
| Regulatory policy and disclosures | Appointment coordination |
| Licensed or authorized activities | Warm or specialist transfers where permitted |
| Final governance | QA, dispositions, campaign reporting, and agreed escalations |
The exact division depends on the product, jurisdiction, regulatory requirements, customer permissions, and the bank’s operating model.
When Does Outsourcing Banking Telesales Make Sense?
Outsourcing telesales is not necessary simply because a bank has a cross-sell campaign. It becomes more relevant when the execution workload begins to exceed what internal teams can consistently manage.
A bank may consider outsourced telesales services when approved campaign volumes repeatedly exceed internal calling capacity, relationship managers spend too much time on repeatable outreach, follow-up varies significantly across teams, or campaigns need additional language or operating-hour coverage. It can also make sense when capacity needs to increase quickly without creating permanent internal headcount for every campaign cycle.
This is where a specialist cross-selling call center or telesales partner should be evaluated on much more than seat availability. The provider needs to work within the bank’s scripts, workflows, technology environment, QA requirements, reporting structure, and compliance controls. If the operating requirement extends beyond existing-customer cross-sell into approved acquisition and conversion activity, customer acquisition services may form another part of the model. The two functions should remain clearly separated according to the campaign objective.
Cross-Selling Existing Customers Is Also a Retention Question
More products per customer should not be treated as the only measure of success. A relevant product introduced at the right time can make the relationship more useful to the customer. Poorly timed, repetitive, or irrelevant outreach can have the opposite effect. That makes banking cross-selling closely connected to customer experience and long-term customer value. The aim should be to work relevant opportunities without turning every interaction into a sales push.
This is also why banks should consider cross-sell performance alongside retention and relationship measures. Our guide to maximizing customer lifetime value through customer retention looks at that broader relationship beyond the individual campaign.
Where retention itself is becoming difficult to manage at scale, dedicated customer retention services can address a different part of the existing-customer lifecycle.
How Should Banks Evaluate a Telesales and Cross-Sell Partner?
A provider should be evaluated on the operating model it can support, not simply on the number of agents available.
- Campaign execution: How will approved customer lists, contact attempts, dispositions, callbacks, and follow-up be managed?
- Quality controls: How are calls monitored, scored, coached, documented, and escalated?
- Compliance alignment: Can the team operate within bank-approved scripts, disclosures, customer permissions, calling rules, and escalation requirements?
- Systems: Can the provider work within the required CRM, dialer, workflow, security, and reporting environment?
- Handoff discipline: Can an interested customer reach the appropriate internal specialist without losing the context gathered during the first conversation?
- Performance visibility: Can leaders see contact rates, customer interest, appointments, transfers, dispositions, QA outcomes, and downstream results rather than only raw call volumes?
These questions help separate simple calling capacity from a genuinely managed telesales operation.
Turn Identified Customer Opportunities Into Executed Conversations
Banks do not always need another model to identify a cross-sell opportunity. In many cases, the opportunity is already sitting inside an approved customer segment. The harder task is working those opportunities consistently enough to reach customers, understand genuine interest, and move the right conversations forward.
Boomsourcing supports banks and other financial services organizations with outsourced telesales services, approved cross-sell campaign execution, customer follow-up, appointment setting, warm transfers, and related customer engagement operations.
The financial institution retains control of product strategy, customer eligibility, pricing, underwriting, regulatory policy, and specialist decisions. Boomsourcing provides scalable execution around the approved customer-contact process. For organizations looking to improve banking cross-selling without simply adding more work to internal relationship managers or sales teams, the first question should be straightforward: where does the approved opportunity stop moving?
Have an approved customer campaign your internal teams cannot work on consistently? Talk to Boomsourcing about extending your customer-contact capacity.

 Connect WITH US

 By Edgar Sainz
 By Rajesh Adhikary
 By Nathan Brown