Lenders spend heavily to acquire personal loan customers. Then they quietly let those same customers drift toward a competitor’s next offer. That gap between acquisition spending and retention effort explains why so many portfolios plateau. Personal loan customer retention services exist to close exactly that gap. They turn a one-time transaction into a lasting lending relationship. For any lender chasing organic growth, repeat borrowers are the most underpriced asset on the books.
Acquisition
Retention
Why Repeat Borrowers Outperform Fresh Leads
A new borrower costs more to acquire than an existing one costs to retain. Every servicing call builds equity with someone who already trusts your brand. So does every renewal reminder and well-timed cross-sell offer. American households now carry $277 billion in personal loan debt. That volume spans 26.4 million accounts, according to LendingTree’s most recent data. Meanwhile, millions of borrowers are deciding right now whether to return to the same lender. Consequently, retention is not a soft metric tucked into a quarterly report. It is a revenue lever sitting in plain sight.
Personal Loan Customer Retention Services: Where the Real Cost Hides
Silence is expensive in lending. A borrower who finishes repayment without hearing from their lender assumes the relationship ended. JD Power’s 2026 Consumer Lending Satisfaction Study found personal loan satisfaction rose to 706 out of 1,000 points. However, nonbank lenders are closing the loyalty gap with banks across nearly every touchpoint, per The Financial Brand’s analysis. That shift matters because lost loyalty rarely returns through advertising alone. Structured personal loan customer retention services fill that silence with scheduled check-ins and payment milestone calls. They also add proactive outreach before a competitor’s offer reaches the borrower’s inbox. The lenders winning this decade treat retention as infrastructure, not an afterthought.
Personal Lending Upselling Outsourcing: One Loan Should Never Be the End
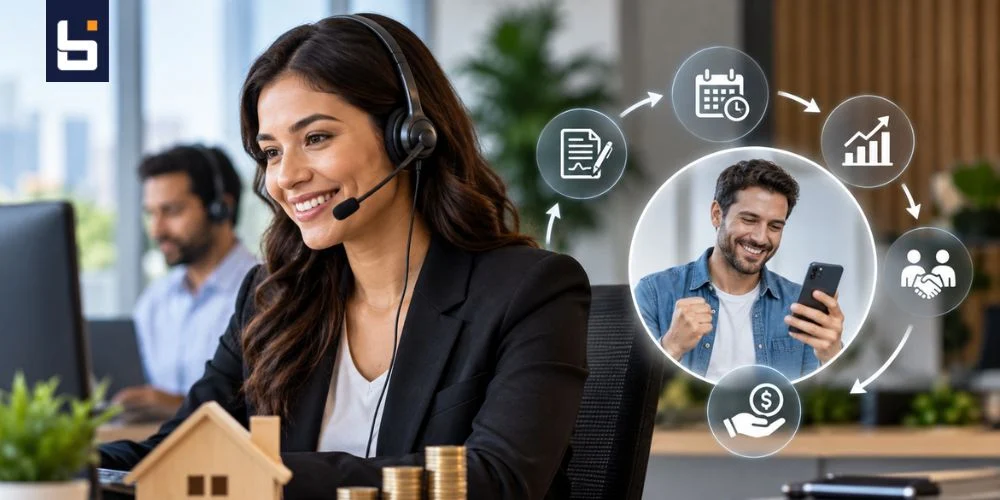
Every closed loan is also an open door. A borrower who repaid responsibly has already proven creditworthiness. So the next conversation should feel like a natural next step, not a hard sell. Personal lending upselling outsourcing works because trained telesales agents spot the right moment. That moment might be a loan nearing payoff, a mentioned life event, or an improved credit profile. Boomsourcing’s own upselling and cross-selling programs follow that same principle. They match the offer to the borrower’s stage instead of pushing a generic script.
Timing the Conversation Correctly
Cross-selling too early feels transactional. Waiting too long feels careless instead. The sweet spot sits near the final third of a loan term. That’s when a borrower naturally starts thinking ahead. Agents who reference payment history build instant credibility. That credibility converts far better than any cold pitch, no clipboard-and-script energy required.
Repeat Borrower Telesales BPO: Compliance Without Losing the Human Touch
Financial services telesales lives under tight regulatory scrutiny, and rightly so. A repeat borrower telesales BPO partner must run TCPA-compliant scripts and log every call. Still, agents need to sound like humans who remember the borrower’s name. That balance is harder than it sounds, especially at scale. However, the payoff is significant. Agents blending compliance discipline with genuine rapport consistently outperform scripts that read like legal disclaimers. Boomsourcing’s personal lending programs pair certified compliance frameworks with agents trained specifically for lending journeys. As a result, retention calls never feel like a liability exercise.
A Lesson From the Field: Nearshore Loan Servicing Done Right
A fintech lender recently scaled its loan processing through a nearshore BPO partnership. The partner handled both inbound customer service and loan servicing, according to a documented case study from Auxis. The lender needed English-fluent, culturally aligned agents who could hold complex loan conversations. Those agents also needed to sound natural, not scripted. The result was a servicing operation that scaled through seasonal spikes while keeping compliance intact. Admittedly, not every lender needs a nearshore setup. Still, the underlying lesson travels well. Servicing quality and retention are inseparable, and cutting corners on either one shows up within a quarter.
What Industry Leaders Are Telling Lenders Right Now
Ronnie Allan, PNC’s Head of Consumer Credit Card and Personal Lending, says lenders must help borrowers understand “the long-term impact of their borrowing decisions.” That guidance applies just as much to retention as it does to origination. Borrowers who feel understood tend to stay. Borrowers who feel processed tend to leave. Interestingly, the funniest habit in this industry is simple. Lenders spend fortunes chasing new leads while loyal customers wait by a phone that never rings.
Building a Retention Program That Actually Compounds
A durable program blends three elements. It needs consistent outreach, well-timed cross-sell offers, and agents who understand regulation as well as they understand people. Lenders exploring this space often start with the same qualification discipline used in personal and commercial loan lead generation. Then they extend that rigor into the full servicing lifecycle. Over time, retained borrowers refer friends and return for larger loans. They also cost far less to serve than any newly acquired lead. That compounding effect, more than any single campaign, separates steady growers from lenders stuck refilling a leaky funnel.
A Quick Reality Check for Marketing Teams
Chasing a new borrower usually costs several times more than keeping one. Yet most lending marketing budgets still lean almost entirely toward acquisition. Rebalancing even a modest share toward retention and cross-sell telesales tends to pay for itself within a single loan cycle.
Ready to Turn Repeat Borrowers Into Your Best Growth Channel?
Boomsourcing builds personal loan customer retention services and telesales programs made for regulated lenders. Our teams handle compliance, timing, and rapport, so you do not have to choose between them. Talk to our team about a retention and cross-sell strategy built around your existing borrower base, and start converting loyalty into measurable, organic growth today.

 Connect WITH US

 By Edgar Sainz
 By Rajesh Adhikary
 By Nathan Brown